Best Money Apps in 2026: 8 Tools to Save and Invest
Your phone can now do the work that once required a banker, a broker, and a shoebox full of receipts. The best money apps in 2026 help you budget, automate savings, invest spare change, and track every subscription from one screen. The hard part is not finding an app, it is choosing the right few from thousands of options.
This guide breaks the field into clear categories so you can build a small, powerful stack instead of cluttering your home screen. Each pick solves a specific job, and together they cover the full money journey from first paycheck to first investment.
What makes the best money apps worth installing
A great financial app earns its place by saving you time or money, not just by looking sleek. Before you download anything, judge each candidate against a short checklist.
- Security: bank-level encryption, two-factor authentication, and read-only account access.
- Transparent fees: no hidden monthly charges buried in the fine print.
- Automation: recurring transfers and round-ups that run without reminders.
- Insured partners: deposits held at FDIC-member banks.
- Clear data: dashboards you can understand at a glance.
Insurance matters more than most people realize. You can confirm whether a partner bank is covered using the FDIC BankFind directory before you move a single dollar.
Best money apps for budgeting and tracking
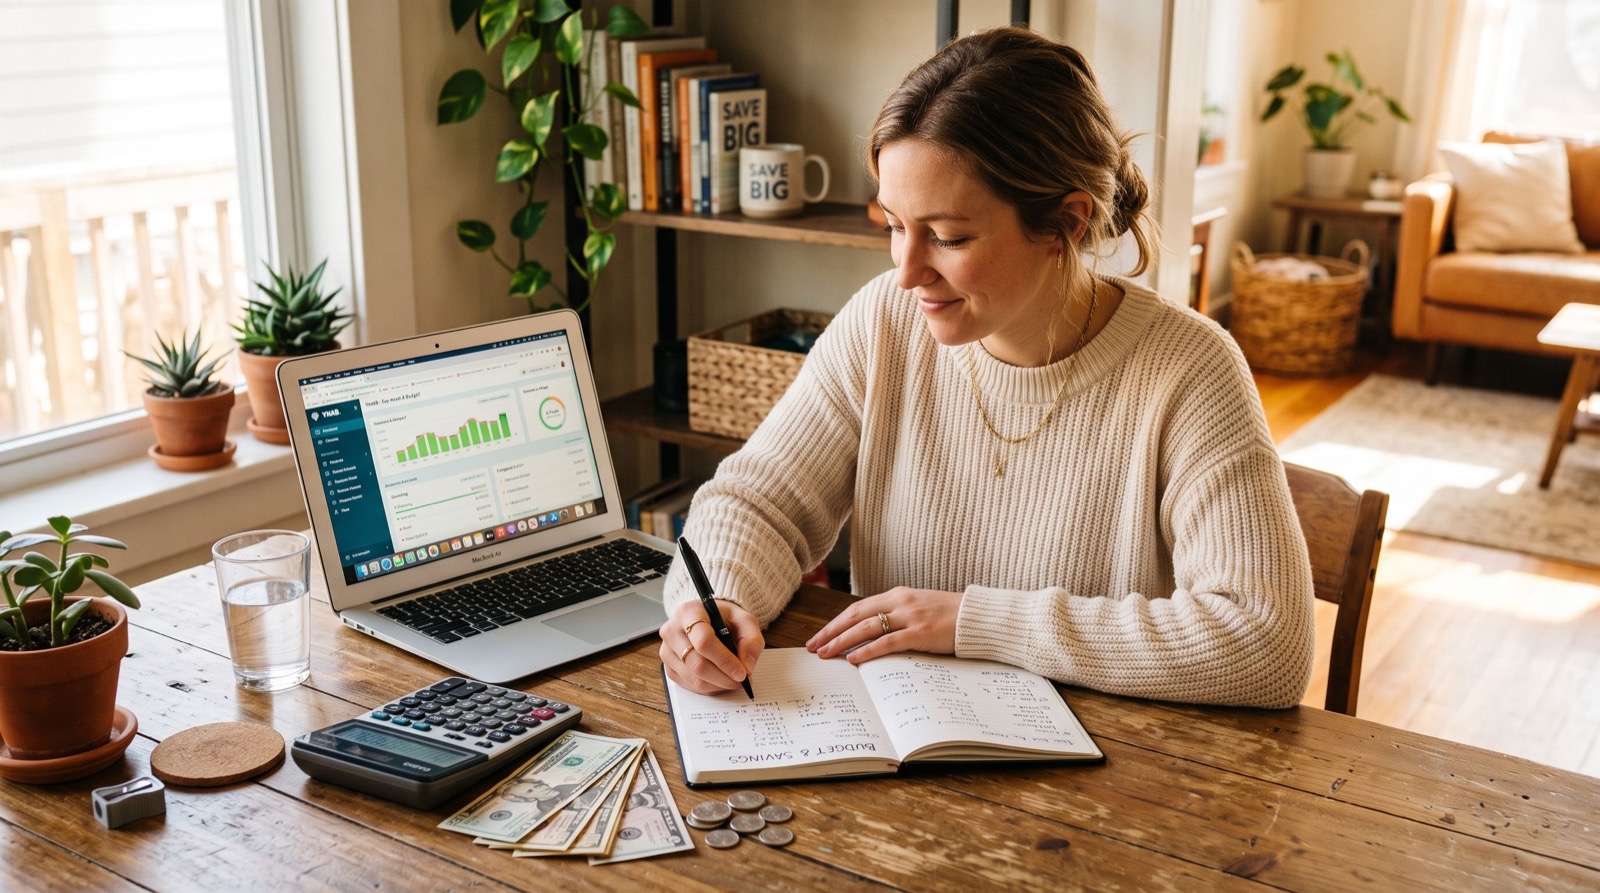
Budgeting apps form the foundation of any stack because they show where your money actually goes. Most connect to your accounts, categorize transactions automatically, and flag overspending in real time.
Look for one that supports custom categories and shared household access. The goal is a single dashboard that answers one question instantly: can I afford this right now?
Apps for saving, investing, and payments
Once your budget is stable, automation does the heavy lifting. Saving and investing apps move small amounts consistently so you never have to remember. Payment apps, meanwhile, make splitting bills and sending cash instant.
If peer-to-peer payments are your priority, this detailed Cash App guide walks through setup, fees, and safety features step by step. Pair a payment app with a dedicated savings app and a long-term investing app, and you cover nearly every daily money task.
Compare the top money app categories
Use the table below to match each category to the job you need done most urgently.
| Category | Main job | Typical cost | Best feature |
|---|---|---|---|
| Budgeting | Track spending | Free to $15/mo | Real-time alerts |
| High-yield savings | Grow cash | Free | Automatic round-ups |
| Micro-investing | Build a portfolio | Free to $5/mo | Fractional shares |
| P2P payments | Send money fast | Free (instant fees apply) | Instant transfers |
How do I choose the right money app?
Start with your biggest pain point, not the flashiest feature. If overspending is your problem, a budgeting app comes first. If you never save, an automatic round-up app wins. Follow these steps to build your stack without overload.
- Name the single money habit you most want to fix.
- Pick one app that targets that exact habit.
- Use it consistently for 30 days before adding another.
- Confirm the app and its partner bank are insured.
- Review fees quarterly and drop any tool you ignore.
This slow approach prevents the common trap of installing six apps, feeling overwhelmed, and quitting all of them. One original tip: keep your payment app on a separate home screen from your investing app, so spending and saving never sit one tap apart.
Avoid common money app mistakes
Even great tools can work against you if you misuse them. Watch for the pitfalls that quietly erode your progress.
Instant-transfer fees are the most common. Standard transfers usually take one to three business days and cost nothing, while instant transfers often carry a percentage fee. Unless you genuinely need the cash now, wait and keep the fee in your own pocket.
Another mistake is chasing promotional interest rates without reading the terms. A high introductory rate that drops after three months may underperform a steady account. When you need help vetting a provider or untangling a complicated transfer, consult reputable service experts rather than relying on marketing claims alone.
Watch out, too, for notification fatigue. If an app buzzes your phone for every single transaction, you will eventually mute it and miss the alerts that truly matter. Customize your settings so you only hear about large purchases, low balances, and unusual activity.
How money apps help you reach specific goals
The real power of a good app stack shows up when you attach it to concrete goals. Abstract saving rarely sticks, but saving for a named target keeps you motivated through the slow middle stretch.
Most savings apps let you create separate pots or envelopes for each goal. Give every pot a clear name and deadline, then set an automatic weekly transfer into each one.
- Emergency fund: three to six months of essential expenses.
- Travel pot: a fixed weekly amount toward your next trip.
- Big purchase: a new laptop, appliance, or deposit.
- Holiday gifts: small year-round contributions to avoid December debt.
Seeing each pot fill up gives you a steady sense of progress. That visible momentum is often the difference between a goal you reach and one you abandon by spring.
Keep your money app stack lean and secure
More apps do not mean more control. Every tool you link to a bank account is another login to protect and another privacy policy to trust. A tight stack of three or four trusted apps beats a cluttered screen of forgotten logins.
Review your connected apps every quarter and revoke access for any you no longer use. Use a unique, strong password for each one, ideally stored in a password manager, and never reuse the password that protects your primary bank account.
Frequently Asked Questions
Which are the best money apps for beginners in 2026?
Beginners should start with one simple budgeting app and one automatic savings app. Master those two before adding investing tools, so your foundation stays solid and stress-free.
Are money apps safe to link to my bank account?
Reputable apps use encryption and read-only access, meaning they can view transactions but not move your money without permission. Always enable two-factor authentication and verify the developer first.
Do the best money apps really cost nothing?
Many core features are free, but premium tiers and instant-transfer fees exist. Read the pricing page carefully so a free app does not quietly become a monthly expense.
Can one app handle budgeting, saving, and investing?
Some all-in-one platforms try, but most people get better results from two or three focused apps. Specialized tools usually offer deeper features and clearer data than a single do-everything app.
Build your money app stack this week
The best money apps work only when you actually use them, so resist the urge to download everything at once. Choose one tool that fixes your biggest frustration, give it a month, and add from there. With a lean, trusted stack in place, your 2026 finances can finally run on autopilot while you focus on the goals that matter.